Key takeaways
- A PE comes from activity, not headcount. A fixed place at your disposal or one person who habitually closes contracts is enough, with no minimum number of staff.
- The home-office line is 50%. Under the OECD’s November 2025 commentary, a home used for less than 50% of working time over 12 months is generally not a PE.
- An EOR does not remove PE risk. It employs the person locally, but what they do for you and any premises you provide still decide the tax outcome.
- Disputes are slow and costly. Treaty cases closed in 2024 averaged 27.4 months, and Kering settled one Italian PE dispute for €1.25bn.
Our take
Most companies treat a first overseas hire as an HR decision and a tax adviser sees it months later. The authority to close deals matters more than the desk location. Write down what each overseas person may sign, negotiate and approve before the contract starts.
Manjuri Dutta, Co-Founder & Editor, EmployerRecordsWhat is a permanent establishment?
A permanent establishment (PE) is a taxable presence that a foreign company has in another country. It exists when the company runs its business through a fixed place there, or through a person who habitually concludes contracts on its behalf. Once a PE exists, that country can tax the profits attributable to it.
The rule sits in Article 5 of the OECD Model Tax Convention, which most bilateral tax treaties copy. Treaties usually raise the bar before a country can tax a foreign company, so read the treaty between the two countries first and local law second.
PE is not tax residency. Residency decides where a company is taxed on its worldwide profits, normally where it is incorporated or managed. A PE only brings the profits of the local presence into the local tax net.
What creates a permanent establishment?
Four routes create most PEs. Each one tests what people and premises do for your business, not how your contracts are labelled.
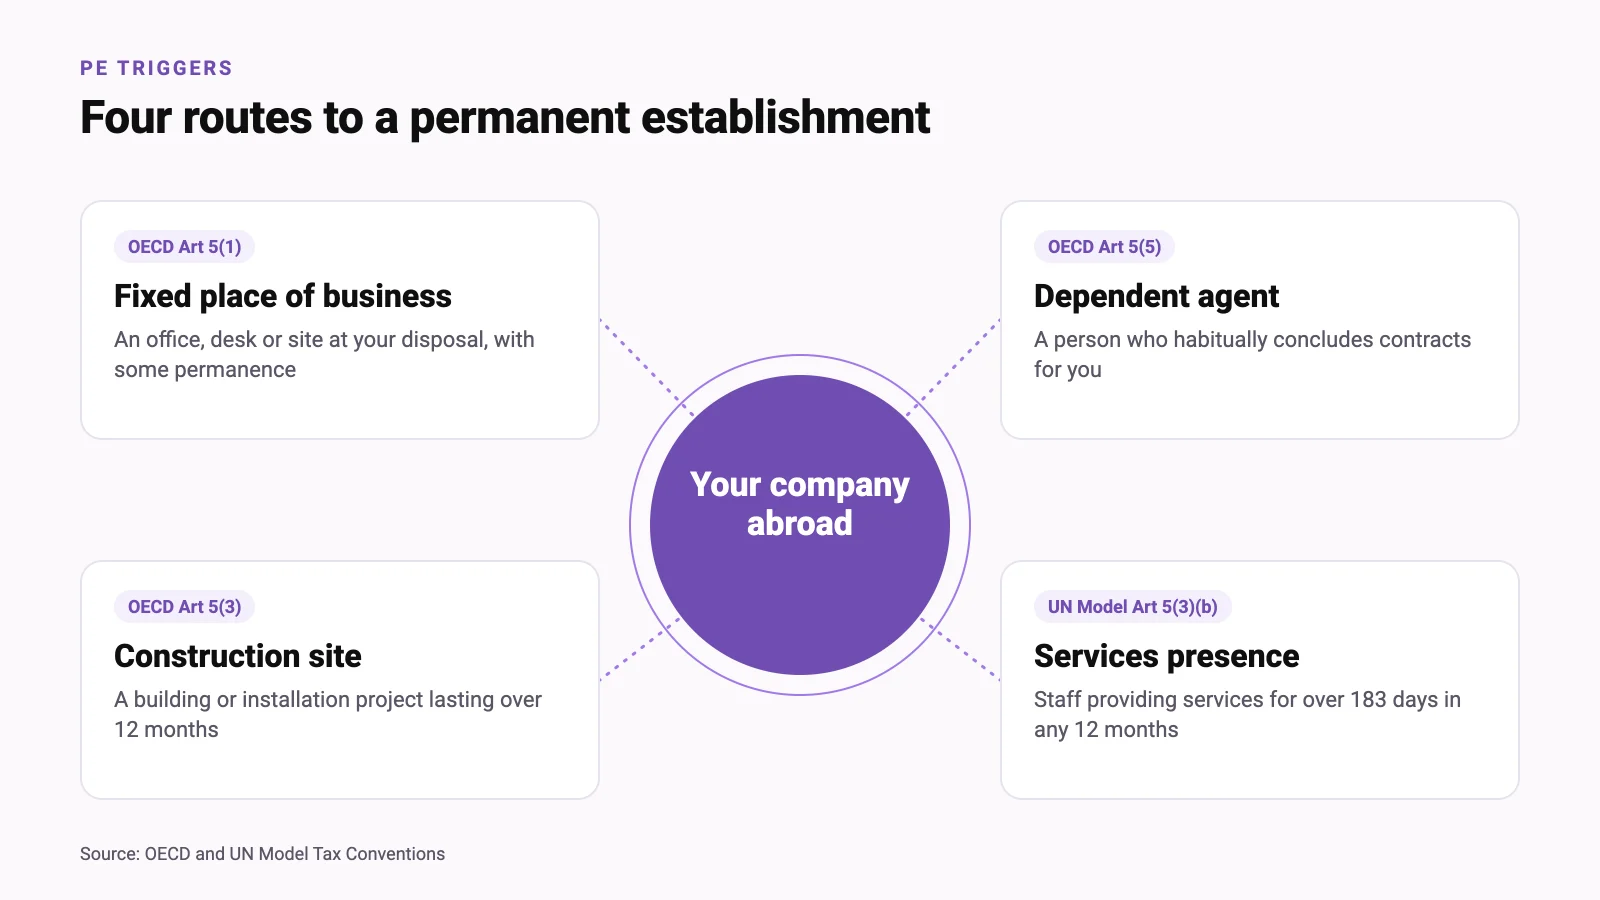
A truly independent agent, such as a distributor acting in its ordinary business, does not create a dependent agent PE. That exception narrowed in 2015 for agents who act almost only for one principal or its related companies. Whether the 2015 wording applies to a given treaty depends on the Multilateral Instrument (MLI), which 105 jurisdictions had signed and 89 had deposited by 6 May 2026.
What does not create a permanent establishment?
Purely preparatory or auxiliary activities do not create a PE under Article 5(4). That covers storing, displaying or delivering goods, buying goods and collecting information for the business.
Generally excluded
- Storing or delivering your goods
- Buying goods in the country
- Collecting market information
- A website with no local people or premises
Not safe just because it looks small
- A core sales, negotiation or approval role
- A warehouse that is central to your model
- Splitting activities across related entities, which the anti-fragmentation rule in Article 5(4.1) looks through
- A server you control, kept in one place, doing more than support work
The test is whether the activity is a real part of your income-producing work. Since the 2017 revision, each excluded activity must itself be preparatory or auxiliary, so a warehouse that is the heart of an online retail model is hard to defend.
Can a remote employee create a permanent establishment?
Yes, but less often than most hiring teams fear. Under the OECD’s 2025 update, a home office is judged by how much working time is spent there and why the person is there.
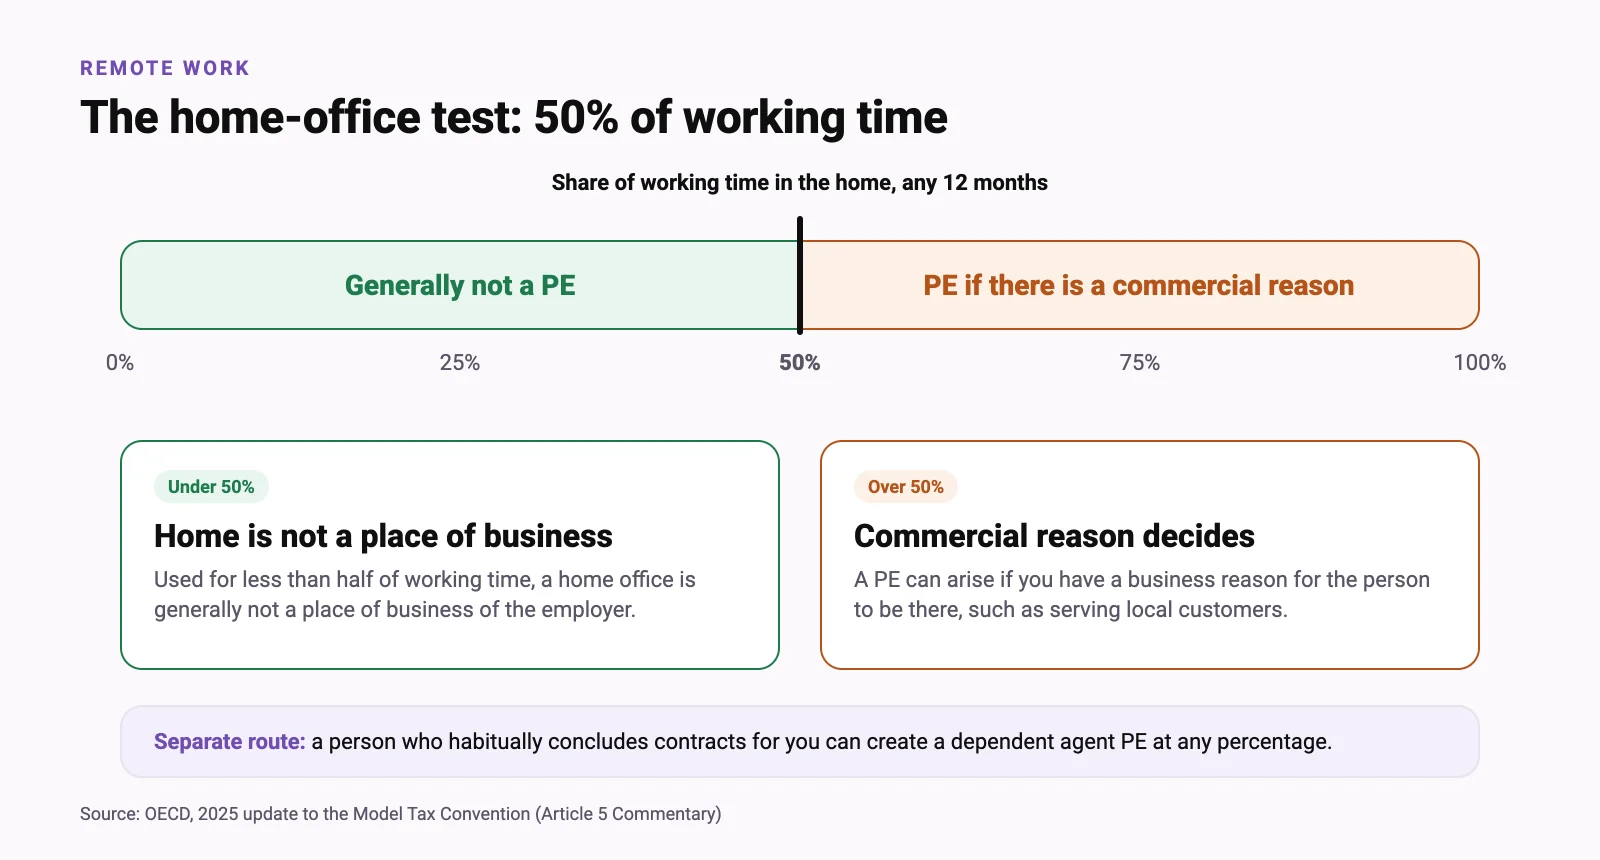
Below 50%, the home is generally not a place of business of the employer. Above 50%, the question becomes whether you have a commercial reason for the person to be in that country, such as serving local customers in their own time zone. Working there for personal reasons does not meet it. The OECD update is guidance, not a treaty change.
The dependent agent route ignores the percentage. A salesperson who habitually closes deals for you can create a PE while working from home one day a week. The 50% line only answers the fixed place question.
Treaties do not update themselves, and a tax authority can read its own treaty differently from the commentary. Treat 50% as a planning line, not a safe harbour.
Which thresholds actually matter?
Several clocks run at once and each answers a different tax question. Mixing them up is the most common planning error.
PE and related thresholds by tax question
| Test | Threshold | What it decides |
|---|---|---|
| Home office (OECD 2025 commentary) | 50% of working time, 12 months | Whether the home is a fixed place of business |
| Construction site (OECD Art 5(3)) | Over 12 months | Whether a project becomes a PE |
| Services PE (UN Model, many treaties) | Over 183 days in 12 months | Whether service staff on site create a PE |
| Dependent agent (OECD Art 5(5)) | No time limit | Whether a contract-closing role creates a PE |
| Employee pay under treaty (Art 15) | 183 days in 12 months | Where the employee pays income tax |
A person can stay under 183 days for personal tax and still create a corporate PE through a contract-closing role. The treaty exemption for employee income tax also fails if a local entity or PE bears the salary, and social security follows separate rules. See the thresholds that turn a remote employee into a tax event and our employer payroll tax rates by country.
Does an employer of record prevent a permanent establishment?
No. An employer of record (EOR) removes the employment risk, not the tax risk. The EOR is the legal employer, but whether you have a PE depends on what the person does for your business.
The EOR carries
- The local employment contract
- Payroll, tax withholding and social security
- Statutory benefits and local registrations
- Employer-side filings
You still carry
- What the person can sign, negotiate or approve
- Any office, desk or equipment you provide
- Local customers served from the home office
- PE assessment, filing and transfer pricing
An EOR still helps. It lets you test a market with one hire and no entity, and it keeps the role to activities that do not bind your company. Give an EOR employee authority to close deals and the tax authority looks through the EOR to the role. For the wider compliance split see remote work compliance through EORs, and for when a local company is the better route see EOR vs entity setup.
Do websites and digital sales create a permanent establishment?
Not under current treaty rules. Selling online to customers in a country, with no people or premises there, does not create a PE. Countries have responded with separate taxes instead.
A digital seller rarely has a PE problem from its website alone. It does face VAT or GST registration and, in some markets, a digital services tax. Check those separately from Article 5.
What do real permanent establishment cases show?
They show that substance beats paperwork and that every outcome is slow and expensive.
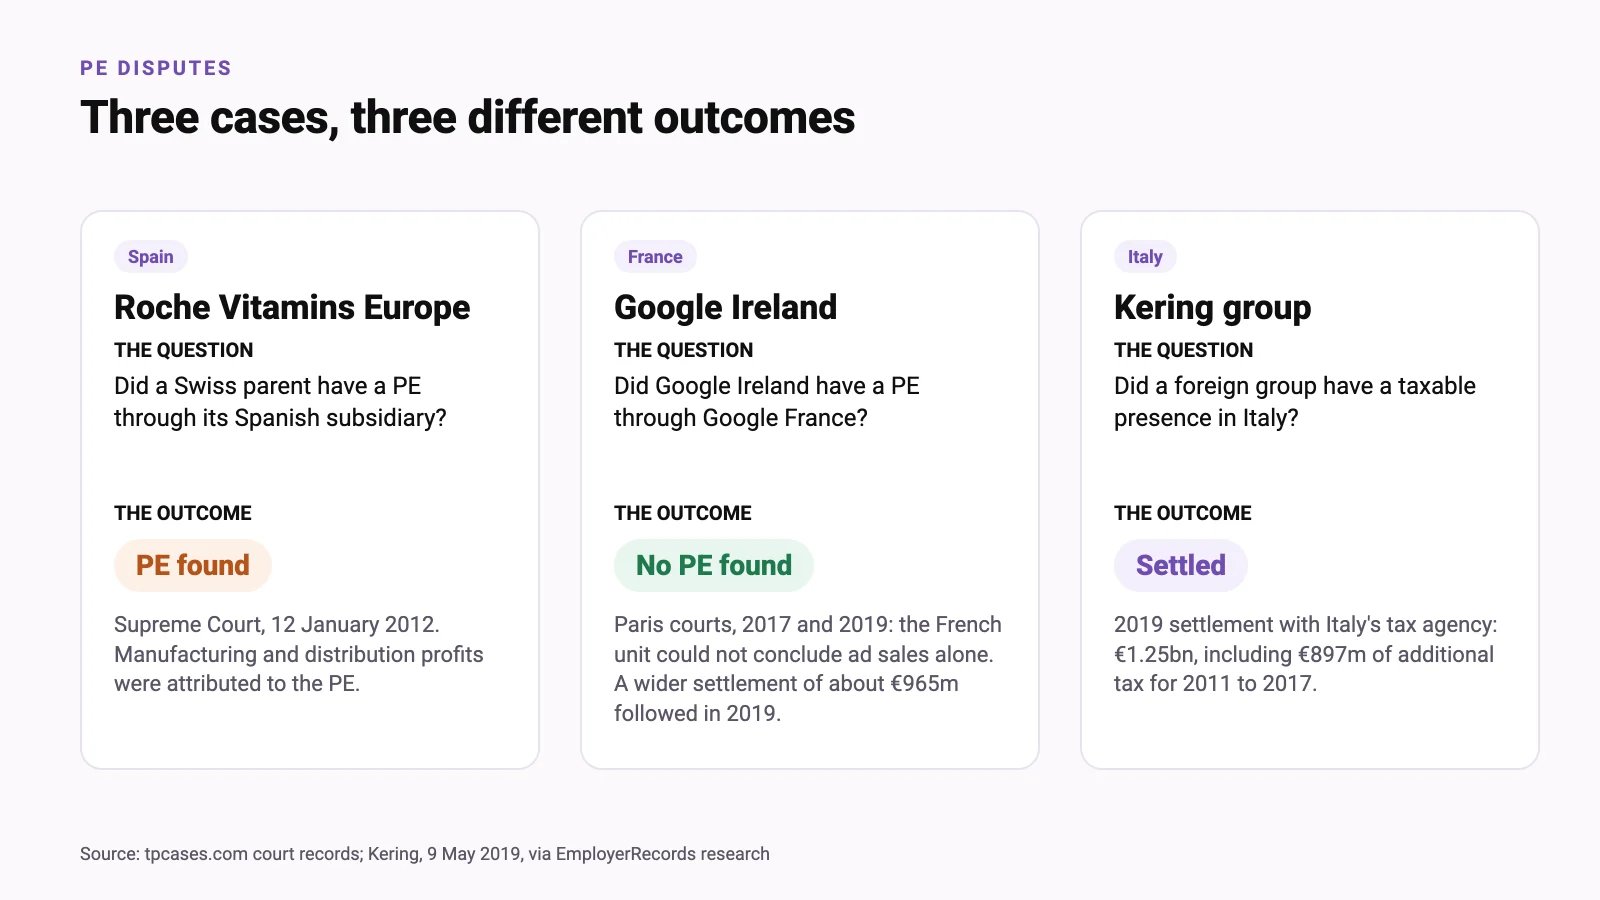
In Spain, the Supreme Court found that Roche’s Swiss parent had a PE through its restructured subsidiary, and it attributed the profits of the work done on the parent’s behalf to that PE (Spain v Roche, 2012). In France, the Paris appeal court in 2019 held that Google Ireland had no PE because Google France could not conclude advertising sales on its own. Google still paid about €965m in a settlement to end the wider French dispute.
In Italy, Kering settled with the tax agency in 2019 for €1.25bn, of which €897m was additional tax for 2011 to 2017 (our compliance data). If you hire in Spain or France, expect these authorities to look at what the role does, not what the contract says.
What happens if you create one by accident?
The country taxes the profits attributable to the PE, usually back to the date it began, plus interest and penalties. The discovery date does not move the start date.
How do you check and reduce permanent establishment risk?
Decide the role’s authority before you decide where the person sits. These six steps cover most first hires abroad.
- Map the roleList what the person will sign, negotiate, approve and where they meet clients. Contract authority is the main trigger.You
- Track the daysRecord working days and home-office share by country against the 50% and 183-day lines.You
- Read the treatyCheck the treaty between the two countries and whether the MLI changed its PE wording.Adviser
- Avoid providing premisesAn office, desk or storage you supply can become a place at your disposal.You
- Limit authorityKeep the role to non-binding work such as lead generation and support, with contracts signed at head office.You
- Pick the structureUse an EOR for non-selling hires, a local entity or branch where the role closes deals. Compare EOR providers if an EOR fits.Adviser
An EOR hire is usually low risk if
- The role supports head office and cannot bind the company
- The person works from home, under half the time or with no local clients
- You provide no local office or equipment
Look at an entity or branch if
- The person closes or negotiates contracts
- They manage a local team or serve local customers daily
- You plan to rent space or hold local stock
Questions about permanent establishment
Short answers to what employers ask most, checked against the OECD, HMRC and our own research on 3 November 2026.
Can a single employee create a permanent establishment?
Yes. Headcount does not matter, activity does. One person who habitually concludes contracts for you, or who works from home more than half the time for a commercial reason, can be enough.
Does having a website create a permanent establishment?
No. A website alone is not a fixed place of business. A server you control, in one location for long enough and doing more than support work, can be.
Does an employer of record eliminate PE risk?
No. It removes the employment and payroll risk. What the person does for your business, and any premises you provide, still decide whether you have a PE.
How long before a permanent establishment exists?
It depends on the route. A dependent agent has no time limit, a construction site needs more than 12 months under the OECD Model, a services PE needs more than 183 days in 12 months, and a home office is tested at 50% of working time.
Is a permanent establishment the same as tax residency?
No. Residency decides where a company is taxed on worldwide profits. A PE only taxes the profits attributable to the local presence.
What happens if a PE is found years later?
The country usually taxes the profits from the date the PE began, with interest and penalties. Keep records of roles, days worked and contract authority so you can argue the true start date.
Do tax treaties always prevent double taxation?
No. They give relief, but you must claim it on time. Treaty disputes closed in 2024 took 27.4 months on average, against an OECD target of 24.
Does the OECD 2025 update change my tax treaties?
Not automatically. It changes the commentary used to interpret the OECD Model, and a tax authority can still read its own treaty differently. Check each treaty and the local authority’s stance.
About the author
Manjuri Dutta is Co-Founder and Content Editor at EmployerRecords.com, covering Employer of Record providers and global hiring platforms. She evaluates providers on entity ownership, statutory compliance, and real pricing rather than vendor claims, and built the verification process used across EmployerRecords' country guides, checking vendor claims against government registries and public filings.
View all articles by Manjuri